A full appointment book does not always mean a profitable salon. Plenty of salons, spas and barbershops are busy every day and still wonder at the end of the month where the money went. The report that answers that question is the profit and loss statement, often called the P&L or income statement.
This guide walks through a salon P&L line by line, shows a complete worked example, explains what a healthy profit margin looks like, and lists the six mistakes that most often make the numbers wrong. The maths is the same in any currency and any country.
What a salon profit & loss statement shows
A P&L covers a period of time, usually a month, a quarter or a year. It answers one question: after paying for everything it took to run the salon in that period, what was left? It is built from four blocks, always in the same order:
| Block | What goes in it in a salon |
|---|---|
| 1. Sales (revenue) | Services, retail products, packages and memberships once they are used, course or training fees |
| 2. Direct costs | The cost of retail products you sold, plus colour, treatments and back-bar products used on clients |
| 3. Operating expenses | Wages and commission, rent, utilities, card-machine fees, marketing, software, laundry, repairs, insurance |
| 4. Net profit | What is left: Sales − Direct costs − Operating expenses |
Sales minus direct costs gives you gross profit. Gross profit minus operating expenses gives you net profit. Divide either one by sales and you have a margin, the number that lets you compare one month with another, or your salon with another salon.
A worked example: one month in a salon
Here is a simple monthly P&L for a salon with a handful of stylists. The figures are an example only, but the layout is exactly what your own report should look like.
| Line | Amount | % of sales |
|---|---|---|
| Service sales | 18,000 | 90% |
| Retail sales | 2,000 | 10% |
| Total sales | 20,000 | 100% |
| Cost of retail products sold | (1,000) | 5% |
| Colour, treatments & back-bar products | (1,600) | 8% |
| Gross profit | 17,400 | 87% |
| Wages & commission | (9,400) | 47% |
| Rent | (3,200) | 16% |
| Electricity, water & internet | (700) | 3.5% |
| Card-machine fees | (300) | 1.5% |
| Marketing | (400) | 2% |
| Software & phones | (200) | 1% |
| Cleaning, laundry & repairs | (300) | 1.5% |
| Insurance & other | (400) | 2% |
| Total operating expenses | (14,900) | 74.5% |
| Net profit | 2,500 | 12.5% |
Three things jump out straight away. Wages are the biggest cost by far, so small changes in how the team is paid move the bottom line more than anything else. Rent is fixed, so every extra client you fit into the same space improves the margin. And the salon keeps 12.5 cents of every sale, which means a 10% discount on a service can wipe out most of the profit on it.
If you run the salon on your own and do not pay yourself a wage, remember that this profit is also your income. A salon that only makes a profit because the owner works for free is worth knowing about early.
What is a healthy salon profit margin?
There is no single right number. Rent, wage levels, the way staff are paid and the mix of services all differ from one city and country to the next. As a rough guide, many owners and business advisers treat a net margin of around 10% as a sound target for a salon, with well-run salons going higher and many small salons earning less.
Two ratios are worth watching even more closely than the final margin:
- Wages and commission as a share of sales. In most salons this is the largest line, often around half of sales. If it climbs month after month while sales stay flat, your pay structure or your booking gaps need attention.
- Retail as a share of sales. Retail usually needs no extra chair time, so salons that sell products well tend to have healthier margins. Watch the direct cost too, and do not let unsold stock pile up.
The most useful habit is not comparing yourself with a national average. It is comparing this month with last month, and with the same month last year, and asking why each big line moved.
Six mistakes that make a salon P&L lie
A P&L is only as good as the entries behind it. These six are the ones we see most often, and every one of them makes the salon look healthier than it is, or hides a problem until the bank balance runs short.
1. Tips counted as sales
A tip belongs to the team member. If it is added to your sales, income looks higher than it is, and the payout later looks like an extra cost. Tips should sit as money owed to staff until they are paid. How to record tips properly.
2. Deposits counted as sales on the day they are paid
A deposit for a wedding or a prepaid package is not earned until the service is done. Counting it early makes this month look great and a future month look terrible, and if the client cancels, the sale never really happened. How to record deposits.
3. Card-machine fees left out
If the card terminal pays you a little less than the card sales, and that difference is never recorded, your books slowly drift away from your bank. Record the fee as an expense so the two always match.
4. The owner’s own spending booked as a salon expense
Groceries, school fees or a family trip paid from the salon account are not salon costs. Booked as expenses, they make the salon look less profitable than it is. They belong in owner’s drawings, which reduce your equity, not your profit.
5. Staff advances booked as wages
Money you lend a team member before payday is not a wage yet. It is money the staff member owes you, and it becomes part of the wage cost when it is taken back from their pay. Booking it as an expense on the day it is handed over puts the cost in the wrong month. Staff loans and advances explained.
6. Big purchases dropped into one month
A new chair, a dryer or a year’s worth of stock is not a one-month cost. Equipment belongs in a fixed asset register and is spread over its useful life. Stock becomes a cost when it is sold or used. Put it all into one month and that month shows a loss that never really happened.
See your own P&L without building it by hand
Make a few test bills in TressyPOS with a tip, a card payment and a deposit, add an expense, then open Profit & Loss. 30 days free, no credit card.
Start Free TrialHow to read your P&L every month: five questions
- Did sales go up or down, and was it services or retail? A drop in services usually means empty chair time; a drop in retail usually means the team stopped recommending products.
- Did wages grow faster than sales? If they did, look at commission rates, overtime and quiet hours that are still paid.
- Which expense line grew the most? Look at the biggest change first, not the biggest number.
- Is the margin moving in the right direction? One bad month is not a trend; three in a row is.
- Does the profit match the cash? If the P&L shows a profit but the bank balance keeps falling, check deposits, stock purchases, loan repayments and the owner’s drawings.
Where TressyPOS fits
TressyPOS is salon software with double-entry accounting built into the till. Every bill, expense, tip, deposit and wage is posted into proper books the moment it happens, so the Profit & Loss is never something you have to build at the end of the month.
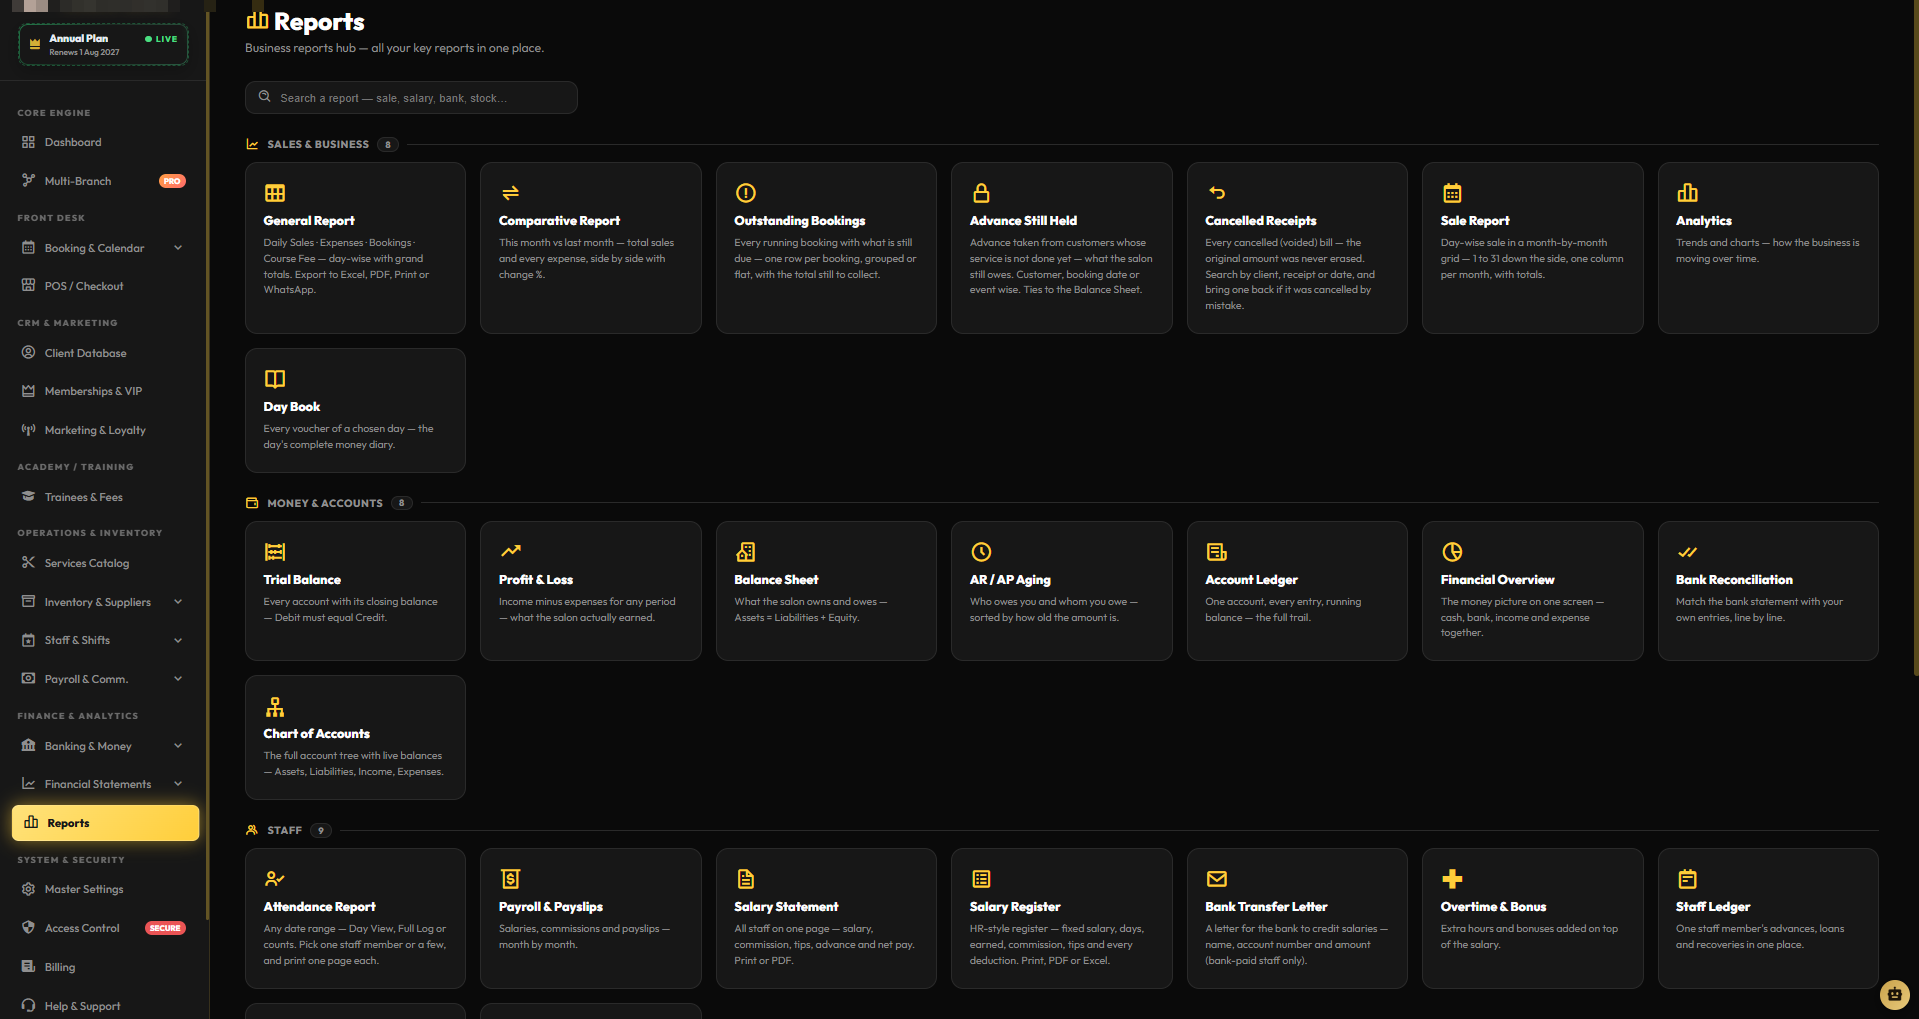
- Profit & Loss for any period, next to the Trial Balance and Balance Sheet, ready whenever you open it.
- A Comparative Report puts this month next to last month, with the change in every sale and expense line.
- Tips go to Tips Payable, deposits to Customer Advances, and tax to its own account, so none of them inflate your sales.
- Card-machine fees can be recorded automatically at the rates you set, so the books match the bank.
- Staff advances are tracked as money owed to the salon, and the owner’s own spending can go to Owner’s Drawings.
- A Fixed Asset Register for equipment, and a Books Health Check that looks for mistakes on its own.
- Works in any browser and as a Windows desktop app, with your own currency and tax name, and billing keeps working when the internet drops.
Need something that fits the way your salon works? Tell us. New features are added regularly, and many of them started as a request from a salon owner.
Every plan includes every feature: $49 a month, $249 for six months or $399 a year, with a 30-day free trial and no credit card required.
The figures in this article are an example, not a benchmark for your salon. This article describes general bookkeeping practice; it is not tax, legal or financial advice.